
Chinese NAND maker Yangtze Memory Technologies (YMTC) moved into third place globally by shipment share for the first time, overtaking Micron; Quanta disclosed a $973 million injection into its US subsidiary and €19.5 million into its German unit; Taiwan’s KMT legislative caucus dropped the freeze motion it had adopted the day before and instead voted to pass the entire NT$63.4 billion drone-related budget in full and other tech news:
I. Semiconductors
1. Phison Electronics: H1 EPS Hits Record NT$187.43 as AI-Driven Enterprise SSD Demand Accelerates
The story: Phison Electronics, Taiwan’s leading NAND flash controller and module maker, reported August 13 that first-half earnings per share reached a fresh high as the company pushes deeper into enterprise SSDs and AI data-storage platforms, with CEO Pua Khein-Seng framing the shift as a move from a dividend-focused business toward a faster-growing one built around enterprise storage.
Key numbers: Second-quarter revenue was NT$67.888 billion, up 65.7% sequentially and 279.5% year-on-year, with gross margin of 65.3% and operating profit of NT$26.370 billion, up more than tenfold year-on-year; net profit reached NT$26.219 billion for EPS of NT$118.57. First-half revenue of NT$108.855 billion already exceeded all of 2025’s NT$72.664 billion, with H1 net profit of NT$41.394 billion and EPS of NT$187.43 — the highest of any Taiwan-listed company so far this half. Inventory turnover days fell to 297 from 315 in Q1; the board declared a NT$60 cash dividend, roughly a 5% yield.
Why it matters: The tenfold operating-profit jump is flattering against a soft Q1 base when inventory was still working down; the more telling signal is structural — enterprise SSD and AI storage revenue is growing fast enough that Phison’s EPS now tops every Taiwan-listed name for the half, echoing the enterprise-storage demand story in Yangtze Memory’s NAND gains below.
2. Yangtze Memory Technologies: Climbs to Third in Global NAND Shipment Share, Though Revenue Ranking Still Trails
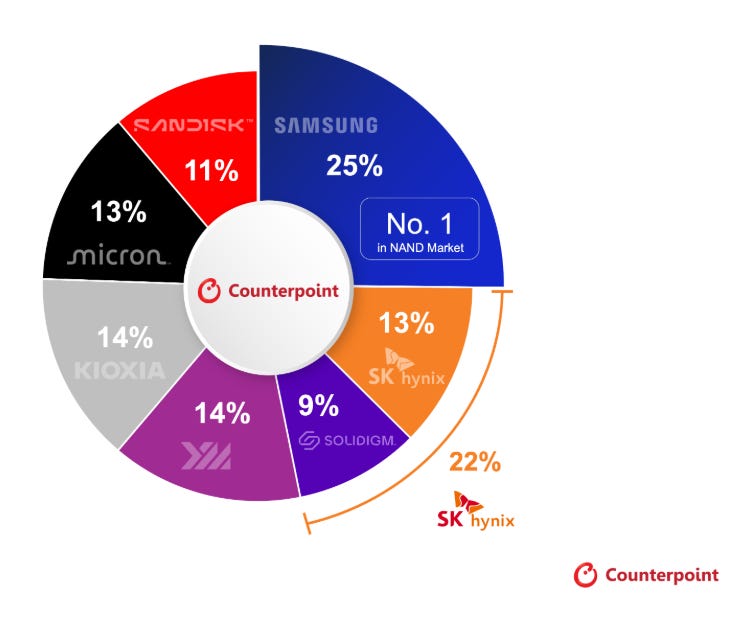
The story: Counterpoint Research’s second-quarter memory tracker, published August 12, showed Chinese NAND maker Yangtze Memory Technologies (YMTC) — founded only in 2016 — moving into third place globally by shipment share for the first time, overtaking Micron and narrowly passing Kioxia.
Key numbers: Samsung led Q2 NAND shipment share at 25%, followed by the SK Hynix group at 22% (SK Hynix 13%, Solidigm 9%); YMTC took third at 14%, edging out Kioxia’s 14% and ahead of Micron’s 13%, with shipments up 22% year-on-year. By revenue, YMTC still ranks fifth, behind Micron and Kioxia, since its mix stays weighted toward lower-priced consumer applications; enterprise eSSD now makes up 48% of global NAND bit shipments, nearly double last year’s 26%. YMTC’s Q1 revenue topped RMB 20 billion, built on 267-layer 3D NAND using its Xtacking 4.0 architecture and immersion DUV lithography rather than EUV.
Why it matters: Shipment-share leadership without matching revenue share means YMTC is winning volume in the cheaper market segment — helped by domestic customers including Xiaomi, Huawei and Lenovo — while still needing enterprise SSDs to close the revenue gap; Counterpoint expects YMTC to pass Micron on revenue in 2027 and, with 400-layer NAND, potentially Kioxia by 2028. For Taiwan’s NAND chain, including Phison above, this bears watching even though pressure stays concentrated in consumer-grade products.
II. Artificial Intelligence
1. Quanta Computer: Raises Capex 33% to NT$40 Billion as AI Server Order Visibility Extends to 2028
The story: Quanta Computer told investors at its August 13 earnings call that AI server order visibility now extends to 2027 and 2028, prompting a raised 2026 capital expenditure guidance, with CFO Elton Yang calling the outlook for the next two years “quite exciting.”
Key numbers: Q2 net profit reached a record NT$28.651 billion, up 35.2% sequentially and 69.9% year-on-year, for EPS of NT$7.43; H1 net profit came to roughly NT$50 billion, EPS NT$12.93, also a record. AI servers made up 75-80% of total server revenue in H1, targeted at 80% for the year, with ASIC-based servers under 10% of that mix; Quanta raised 2026 capex guidance from NT$30 billion to NT$40 billion, targeting year-end capacity double 2025’s, doubling again by 2028. From Q3, some high-value AI server components shift from buy-sell to customer consignment, which management expects will ease working-capital pressure.
Why it matters: Quanta’s customers span all five major cloud providers plus newer NeoCloud AI and ASIC orders, so visibility to 2028 — beyond the usual one-to-two-quarter horizon — reads stronger on spending durability than any single quarter; the profit jump sits atop already-elevated prior quarters rather than a low base, making the capex raise the more useful confirming signal.
2. Quanta Computer: Commits $973 Million to US Expansion, Converts Former AUO Panel Plant for 2028 AI Server Output
The story: Alongside earnings, Quanta disclosed a $973 million injection into its US subsidiary and €19.5 million into its German unit, part of localizing AI server assembly closer to customers, including converting a former AUO panel factory in the Huya Science Park into an AI server plant.
Key numbers: The US injection of $973 million is roughly NT$31.3 billion; the Huya Science Park facility, built for high-voltage panel production, is due for handover in Q4 2027 with mass production targeted for 2028, funded within the raised NT$40 billion 2026 capex guidance above.
Why it matters: Repurposing an idled panel fab rather than building new capacity shortens Quanta’s path to US-based output and signals the AI server chain following customers into US and European geographies rather than staying centralized in Taiwan; the US and German injections are small relative to total capex but geography-specific, positioning Quanta for orders where customers weigh supply-chain location alongside price.
III. Robotics & Industrial Automation
1. Ace Pillar: Automation-Control Revenue Share Jumps to 41.4% as Motion-Control Platforms Enter Humanoid Robot Supply Chains
The story: Ace Pillar (羅昇企業), a Taiwan industrial-automation distributor and systems integrator, reported that its automation-control segment’s share of consolidated revenue rose sharply in H1 as its industrial computing and motion-control platforms — validated by overseas customers — moved into international humanoid robot applications, with general manager Lee Chang-chien framing the technology’s core value as keeping perception, computation, communication and joint control working together reliably.
Key numbers: Automation-control revenue reached 41.4% of H1 consolidated revenue, up from 25.6% a year earlier, climbing to 42.3% in Q2 alone. Global industrial robot installations reached 542,000 units in 2024, a fourth straight year above 500,000, with Asia at 74% of new deployments; global humanoid robot production exceeded 20,000 units in 2025, roughly ten times 2024’s volume, though that multiple is flattering against a very small prior-year base.
Why it matters: A Taiwan automation distributor seeing its highest-margin control-platform segment nearly double as a share of revenue in one year is concrete evidence that humanoid-robot component demand is already showing up in order books, not just prototype announcements; with platforms validated overseas, Ace Pillar supplies multiple integrators rather than betting on one program, in line with the broader Taiwan motion-control ramp visible at peers such as Hiwin.
2. Solomon Technology: Chairman Says Generative-AI Vision Gives Humanoid Robots a “Smart Brain,” Eyes 2028 Commercial Inflection
The story: Solomon Technology chairman Sam Chen told reporters August 13 that the harder problem in humanoid robotics isn’t acrobatics but vision — generative AI is what lets robots reliably recognize and locate objects at a distance, with commercial applications likely to “bloom” as soon as 2028.
Key numbers: Solomon’s active-perception system, cycling through search, selection, zoom and evaluation, can identify objects roughly 5 meters away; the company says software capability currently outpaces hardware readiness. Target applications include solar-panel inspection, warehouse logistics, and factory/telecom-site inspection via quadruped robots and drones; Solomon is working with Compal and Inventec on a domestic humanoid platform pairing a humanoid upper body with a wheeled lower body initially.
Why it matters: Framing vision, not mobility, as the harder problem is a useful corrective for a sector fixated on dexterity demos, and generative AI for synthetic training data addresses robot vision’s most persistent bottleneck: collecting enough real-world images. A 2028 target lines up with the build-outs already under way at suppliers such as Ace Pillar above, suggesting software and hardware are converging on a similar timeline.
IV. Drones & Defense
1. US Army’s Simulated Armored Brigade “Destroyed” by Ukrainian Drone Unit in Joint Exercise, Exposing a Doctrine Gap
The story: The Wall Street Journal reported that during the US Army’s “Joint Resolve” exercise at American bases in Germany this spring, a Ukrainian drone unit — the 412th Unmanned Systems Regiment, with more than four years of combat experience — served as opposing force and effectively wiped out a simulated US armored brigade, forcing the roughly 3,500 American participants to keep “resurrecting” it so the drill could continue.
Key numbers: The unit “destroyed” was the 1st Cavalry Division’s 3rd Armored Brigade Combat Team; the Pentagon has spent what officials describe only as “billions of dollars” on drone-technology development, with no more specific figure disclosed. This is at least the second such result — Ukrainian operators reportedly outperformed NATO forces in a Baltic exercise last May and again in a Swedish-NATO exercise this spring.
Why it matters: CSIS’s Cohen and former Ukrainian armed forces commander Zaluzhny both frame this as confirming drones are now indispensable to modern combat, making traditional maneuver warfare harder to execute; that US forces, despite leading on drone development, have twice been outperformed by battle-tested Ukrainian operators suggests the gap is doctrine and experience rather than hardware. Defense secretary Hegseth’s May move to send more personnel to study Ukrainian drone operations is the clearest sign the Pentagon has registered it — a dynamic keeping demand elevated for Taiwan and allied drone suppliers benefiting from the de-China-fication push described below.
2. Taiwan’s KMT Caucus Reverses Course Again, Passes Full NT$63.4 Billion Drone Budget Ahead of Vote
The story: Taiwan’s KMT legislative caucus reversed course again on August 14, just ahead of the floor vote — dropping the freeze motion it had adopted the day before and instead voting to pass the entire NT$63.4 billion drone-related budget in full, comprising the Ministry of Economic Affairs’ NT$44.2 billion six-year Unmanned Vehicle Industry Development special budget plus NT$19.2 billion in related procurement across other ministries; the caucus also excluded this funding from the government-wide 1.5% budget cut applied elsewhere.
Key numbers: The caucus’s position shifted three times in four days — from an outright cut (August 11) to a freeze motion (August 12-13) to full passage (August 14); it also attached a non-binding resolution requiring the Ministry of Economic Affairs to allocate the six-year special budget evenly by year without exceeding annual caps.
Why it matters: KMT caucus whip Fu Kun-chi and secretary-general Lin Pei-hsiang framed the reversal as building a “second world-class silicon shield” around Taiwan’s drone industry — full passage removes the conditional-release hurdle a freeze would have left in place, a stronger outcome for domestic suppliers than the freeze scenario reported the day before; the caucus said it would strictly enforce the Government Procurement Act to prevent “privileged prime contractors subcontracting out” the work, aiming to keep spending transparent. For Taiwan’s drone suppliers, full passage is a clearer tailwind than a freeze, and ties directly to the shift in global drone demand described above.
V. AI Policy & Geopolitics
1. China’s Silicon Wafer Makers Pour Billions Into Capacity as Beijing Targets 70% Domestic Supply
The story: A wave of Chinese silicon-wafer capacity announcements — led by Eswin Material Technology, TCL Zhonghuan and National Silicon Industry Group — is being driven by AI-linked demand for 12-inch wafers, as Beijing has set a policy target of 70% domestic wafer self-sufficiency for the year.
Key numbers: Eswin Material Technology is investing RMB 6.5 billion for monthly capacity of 1.8 million 12-inch wafers; TCL Zhonghuan is investing RMB 11.96 billion targeting 700,000 wafers a month; National Silicon Industry Group has committed more than RMB 11.4 billion, with Q1 2026 sales up 90% year-on-year. Global wafer shipments reached 3.573 billion square inches in Q2, up 7.4% year-on-year; AI servers consume roughly 3.8 times the 12-inch wafer volume of a standard server, and HBM needs roughly three times the wafer input of conventional DRAM. Qualification cycles for new suppliers still run three months to two years, and incumbents including Shin-Etsu and GlobalWafers retain a long-scale advantage.
Why it matters: The 3.8x and 3x wafer-intensity multiples for AI servers and HBM are the concrete mechanism linking the AI buildout to wafer demand, not just a policy talking point, and explain why Beijing will underwrite billions of RMB against established suppliers; a 70% target this year is aggressive given multi-month-to-multi-year qualification cycles, so a more realistic near-term outcome is domestic makers capturing lower-spec share first — a pattern already visible in Yangtze Memory’s NAND gains above.
2. Huawei Moves Up Flagship Launch to September, Debuts New Chip Design Aimed at Bypassing Advanced-Lithography Curbs
The story: Huawei is reportedly preparing to break from its usual autumn schedule and launch its Mate 90 series in Shenzhen on September 23 — after a Mate XT2 tri-fold event in early September — positioning it against Apple’s own September event, where Apple is said to be targeting 25% first-year share for its foldable phone.
Key numbers: Huawei’s Pura X Max series has sold more than 600,000 units in three months, and the Enjoy 90 Pro Max more than 3 million in the same window; the new Mate series is expected to debut a chip Huawei calls the “Kirin 9050 Pro,” built around a “Tao’s Law” design philosophy meant to lift performance and efficiency without advanced EUV lithography.
Why it matters: Huawei’s claim that the new chip achieves performance “equivalent to” an industry 3nm-class process is a company statement rather than an independently verified benchmark, and warrants caution given Huawei’s continued lack of EUV access under US export controls; even a fraction of the claimed gain would show how far Chinese chipmakers can push mature-node manufacturing before EUV access becomes the binding constraint — the same question shaping how much runway China’s wafer-capacity buildout above has before hitting a technology ceiling rather than a capacity one.
3. More Than 40 Taiwan Listed Companies Post Record H1 EPS as TAIEX Reclaims 46,000 on AI-Driven Earnings
The story: More than 40 Taiwan-listed companies had posted record H1 earnings per share as of August 13, with tech heavyweights leading a 503-point single-day rally that pushed the TAIEX to close at 46,021, reclaiming 46,000 for the first time since a July selloff.
Key numbers: TSMC’s H1 EPS reached NT$49.32, a record for two straight quarters; Foxconn’s H1 EPS hit NT$7.84, also a record for the period. Nanya Technology’s EPS of NT$23.38 drew more than 78,000 lots of net foreign buying this week, the largest of any stock, while Etron, ESMT and Walton Advanced Engineering each saw net buying of 12,000-35,000 lots; Taishin Securities Investment Consulting’s Huang Wen-ching pointed to memory pricing as a specific driver.
Why it matters: Buying concentrated in memory names — Nanya, Etron, ESMT — points to HBM and conventional DRAM pricing as the segment investors see as still under-appreciated, the same dynamic behind China’s wafer-capacity buildout above and Phison’s record results in the semiconductor section; more than 40 companies simultaneously hitting record H1 EPS is a broad-based signal, reinforcing that AI-linked demand spans multiple layers of Taiwan’s supply chain, not just the largest chipmakers.
Global Market Watch is a daily market intelligence report produced in collaboration between TechSoda and FCC Partners, a Taiwan-based investment bank. We curate and analyze the latest developments across AI, semiconductors, drones & defense, robotics & industrial automation, and policy & geopolitics to keep you informed of the trends shaping global markets.
Disclaimer: Any discussion of stock prices, market performance, or specific companies in this article is provided solely for informational and educational purposes. It should not be construed as investment, financial, or trading advice, nor as a recommendation to buy, sell, or hold any securities. Readers should conduct their own research and consult a qualified financial adviser before making any investment decisions.