
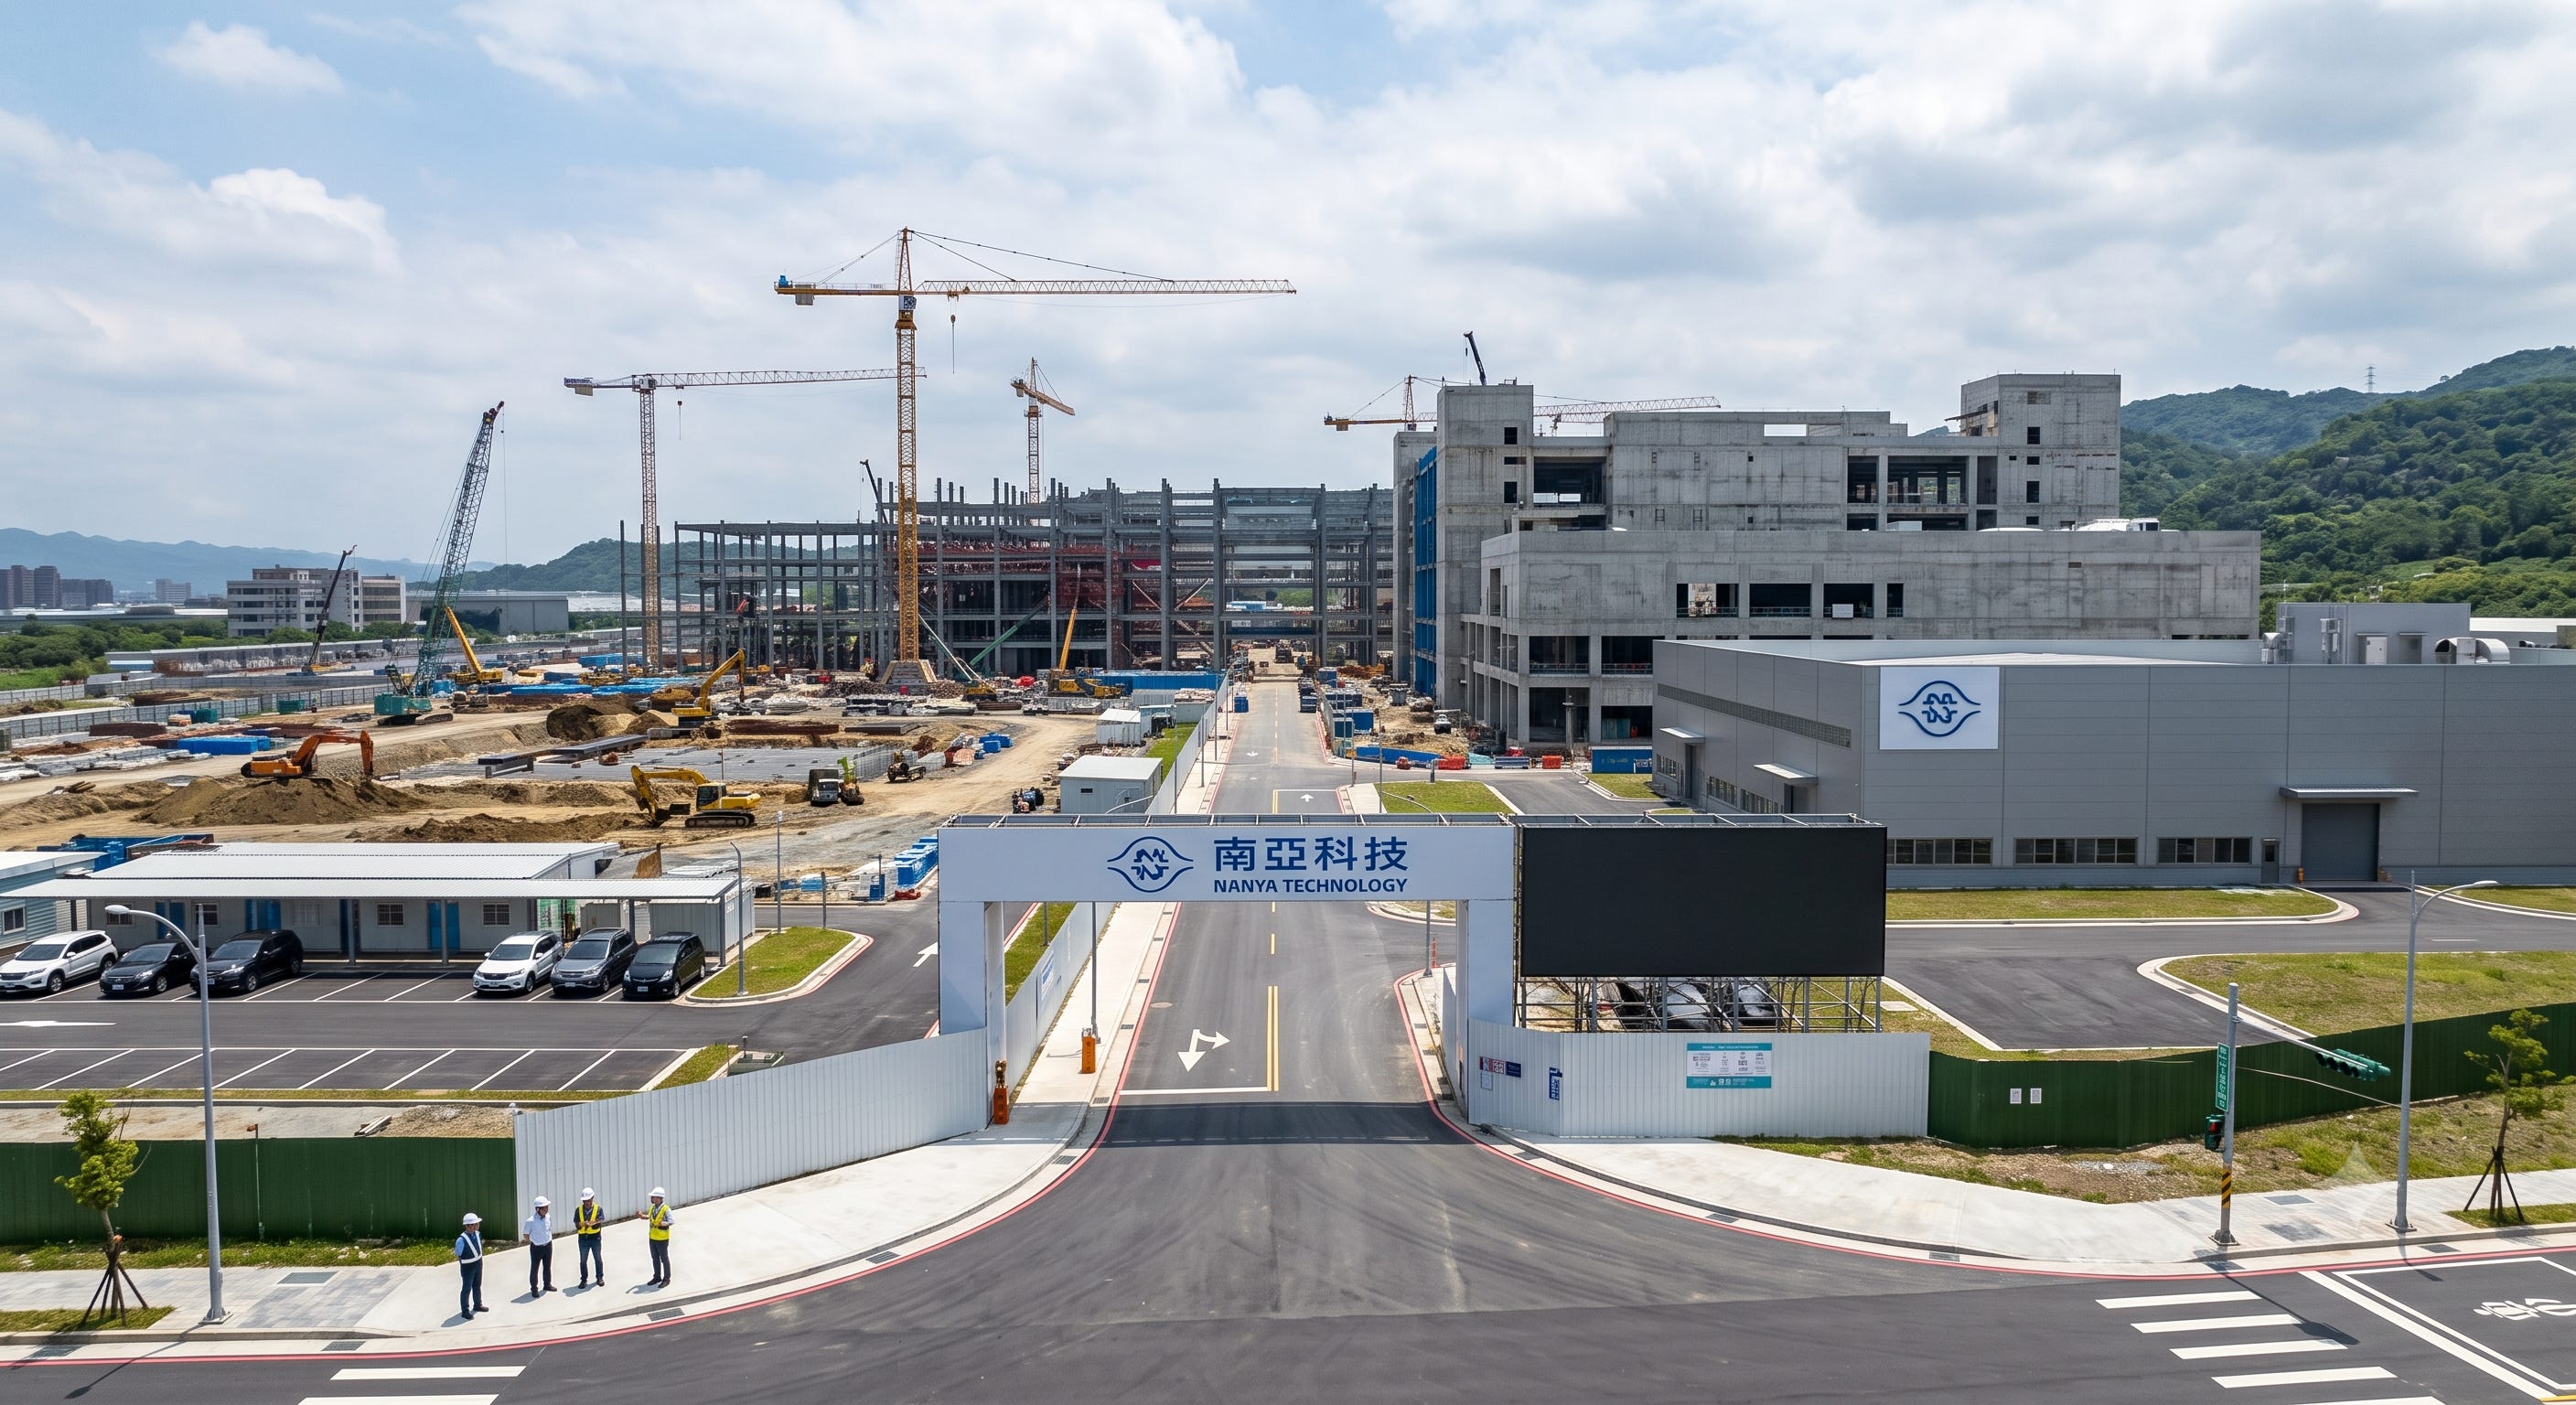
Mega-scale AI infrastructure investments, record-breaking corporate revenues, and escalating technology trade tensions dominated today's news, underscoring Taiwan's central position in the global artificial intelligence (AI) expansion. Highlights include Nanya Technology’s landmark NT$346.6 billion (around USD$10.75 billion) fab commitment—Taiwan's largest chip investment in two decades—and Foxconn’s record NT$946.5 billion July revenue, alongside SpaceX’s exclusive multi-gigawatt commitment to Nvidia for orbital AI data centers. Meanwhile, as Washington and Beijing trade regulatory restrictions over advanced robotics and drone export controls, Taiwan is bolstering its supply chain advantage, backed by a record NT$182.3 billion government science budget and a highly profitable market-stabilization exit anchored by TSMC.
I. Semiconductors & AI Hardware
1. Nanya Technology: NT$346.6B Investment in 5A DRAM Fab
The Story: Nanya Technology confirmed a four-year capital expenditure program (2026–2029) to construct its “5A” advanced DRAM facility, marking Taiwan’s largest single chip project in two decades. To support this, the company raised its 2026 capex guidance from NT$52 billion to NT$69.7 billion.
Key Numbers:
NT$346.6 Billion (~$16 Billion USD): Total investment through 2029.
+34% YoY: 2026 capex increase (raised to NT$69.7B).
35,900 to 45,000 Wafers/Month: Phase 1 target scaling to full capacity.
H2 2027 Target: Production kickoff for EUV-equipped 10nm-class process, ramping to 30,000 wafers/month in 2028.
Why It Matters:
Strategic: Positions Nanya in the high-demand, advanced 10nm-class DRAM segment driven by AI, closing the gap with global leaders Samsung, SK Hynix, and Micron.
Investment Read-Through: Equipment and construction vendors will benefit from early order flow, though Nanya faces near-term free cash flow pressure until the 2027 production ramp begins generating revenue.
2. Nvidia & SpaceX: Orbital AI Data Center Buildout
The Story: SpaceX CEO Elon Musk confirmed that SpaceX will exclusively use Nvidia chips—specifically the Vera Rubin architecture—to power its planned AI data center infrastructure and “Starmind AI” satellite compute network.
Key Numbers:
>2 GW: Targeted compute capacity by end-of-year 2026.
10 GW: Targeted compute capacity by 2027 (a 5x year-over-year increase).
Next-Year Launch: Initial deployment of “Starmind AI” satellites carrying Vera CPUs and Rubin GPUs.
Why It Matters:
Strategic: Reaffirms Nvidia’s position as the default hardware platform for mega-scale AI infrastructure—even as tech giants push custom silicon—and expands its reach into orbital computing.
Investment Read-Through: Provides multi-year demand visibility for Taiwan’s Nvidia supply chain, particularly CoWoS advanced packaging providers, server ODMs, and liquid-cooling component manufacturers.
II. Artificial Intelligence
1. Foxconn: Record NT$946.5 Billion July Revenue
The Story: Driven by surging AI server shipments within its cloud networking segment, Foxconn reported record-breaking monthly revenue for July, surpassing the NT$900 billion threshold for the first time.
Key Numbers:
NT$946.5 Billion: Record July revenue (all-time monthly high).
NT$5.59 Trillion: Cumulative Jan–July revenue (record high).
Q3 Outlook: Management guides sequential and year-over-year revenue growth.
Why It Matters:
Strategic: Validates Foxconn’s structural shift from a smartphone assembly business to an AI infrastructure-led revenue model, with AI servers leading growth.
Investment Read-Through: Investors should watch the upcoming analyst briefing regarding the Vera Rubin server ramp and foldable iPhone outlook to see if smartphone margin softness offsets AI growth.
2. Chunghwa Telecom: ICT Revenue Up 32% on Global AI Expansion
The Story: Chunghwa Telecom reported strong first-half financial results, revealing that H1 contract signings for Information and Communications Technology (ICT) surpassed the total contract value generated in all of 2025. Growth was anchored by domestic AIDC capacity pre-bookings and a massive US expansion.
Key Numbers:
NT$2.68: H1 2026 EPS (beating high-end guidance).
+32% YoY: ICT services revenue growth.
+80% YoY: H1 ICT contract value (matching full-year 2025 totals).
+1,157% YoY: US market revenue growth, driven by a major Texas AI supply chain project.
Why It Matters:
Strategic: Marks Chunghwa’s transition from a domestic telecom provider to an international AI infrastructure player.
Investment Read-Through: While the massive US revenue jump is off a small baseline, the 80% surge in contract value provides strong backlog conversion visibility extending into 2027.
III. Robotics & Industrial Automation
1. Techman Robot & Aurotek: Partnering on Nvidia’s Jetson Thor Platform
The Story: Nvidia CEO Jensen Huang framed robotics as “the next wave of AI,” introducing new Jetson T3000/T2000 platforms and open-sourcing the Alpamayo 2 model. Taiwan’s automation vendors were officially named key ecosystem partners for commercializing physical AI.
Key Numbers:
Techman Robot: Q2 revenue of NT$512 million (+29.6% YoY); H1 revenue up 11.7% YoY to NT$995 million.
Aurotek: Q2 revenue reached NT$902 million (+49.8% YoY, +16.7% QoQ), approaching a 10-year high.
Ecosystem Partners: Advantech and Linova were also named alongside Techman and Aurotek.
Why It Matters:
Strategic: Official ecosystem integration lowers technical barriers for Taiwanese vendors, enabling them to monetize existing industrial client networks via edge-AI robotics.
Investment Read-Through: The Jetson ecosystem effect is already materializing in top-line revenue growth rather than remaining a speculative addressable market story.
2. Unitree Robotics: US Restrictions Target Chinese Humanoid Robots
The Story: The US FCC added “advanced robotics equipment” to its restricted list, banning imports of new Chinese-made humanoid and quadruped models. The move specifically targets manufacturers like Unitree Robotics as the US moves on defense and legislative fronts to limit reliance on Chinese hardware.
Key Numbers:
~90%: China’s current estimated share of global humanoid robot manufacturing.
$5 Trillion: Projected global humanoid market size by 2050 (>1 billion units).
Policy Tools: FCC import ban, NDAA Section 163 (Pentagon ban), and the proposed GUARD Act targeting Chinese robotics government-wide.
Why It Matters:
Strategic: Indicates that the US views China’s near-monopoly in robotics manufacturing with the same strategic urgency as semiconductors.
Investment Read-Through: Western buyers face increasing pressure to source non-Chinese alternatives, creating a “friend-shoring” market opportunity for Taiwanese automation and component suppliers.
IV. Drones & Defense
1. China Tightens Drone Export Controls to the US
The Story: China’s Ministry of Commerce enacted retaliatory measures following US forced-labor entity additions, imposing tighter export controls on drones and critical components bound for the US while halting factory inspections by US certification bodies.
Key Numbers:
6 US Entities: Sanctioned under China’s Anti-Foreign Sanctions Law.
1 Investigation: National security probe initiated regarding imported printing/copying equipment.
Why It Matters:
Strategic: Forces Western defense and industrial buyers to accelerate “de-China” supply chain shifts.
Investment Read-Through: Acts as a sustained, non-temporary supply chain tailwind for Taiwanese drone assemblers positioning to capture Western market share.
2. Elan Microelectronics: Price Hikes and Drone AI Expansion
The Story: Elan Microelectronics announced a 5–10% price increase to offset elevated raw material and foundry costs. Simultaneously, the firm began shipping drone AI Box units in partnership with Thunder Tiger to expand beyond its core consumer IC footprint.
Key Numbers:
5% to 10%: Product price increases effective July 1.
NT$3.21 Billion: Q2 consolidated revenue (+5.7% YoY).
47.4%: Q2 gross margin (held nearly flat, down just 0.6 percentage points YoY).
NT$879 Million: Q2 net income (+149% YoY; EPS NT$3.07). H1 cumulative EPS stands at NT$5.53.
Why It Matters:
Strategic: Elan is diversifying into defense and drone AI edge-processing to establish a second structural growth driver alongside AI PCs.
Investment Read-Through: Margin resilience despite cost inflation underscores strong pricing power, while early drone AI Box shipments offer incremental upside.
V. AI Policy & Geopolitics
1. Executive Yuan: NT$182.3 Billion S&T Budget for Sovereign AI
The Story: Taiwan’s Executive Yuan approved a record-high 2027 Science & Technology budget of NT$182.3 billion (excluding defense). This marks the fourth consecutive year of budget expansion to support sovereign AI, semiconductors, and next-gen tech under “Smart Nation 2.0.”
Key Numbers:
NT$182.3 Billion: Total 2027 budget (+9.47% YoY), up from NT$138.3B in 2023.
NT$20.7 Billion: Taiwan Chip Creation allocation.
NT$10.8 Billion: Net-zero Technology allocation.
NT$8.4 Billion: Greater Southern Silicon Valley initiative.
NT$6.9 Billion & NT$2.2 Billion: Space Program Phase 3 and Smart Robotics, respectively.
Why It Matters:
Strategic: Solidifies sovereign AI compute and local hardware dominance as explicit national security and economic priorities.
Investment Read-Through: Direct government funding guarantees steady order pipelines for domestic semiconductor firms (via Chip Creation) and provides direct policy support to the robotics supply chain.
2. National Stabilization Fund: Exits Operation with NT$9.9B Profit
The Story: Taiwan’s National Stabilization Fund fully closed its ninth market-support operation (active April 2025–May 2026 to buffer US reciprocal tariff volatility). The fund sold off all holdings, recording a substantial profit led primarily by TSMC.
Key Numbers:
NT$9.93 Billion: Total profit on an NT$12.25 billion capital cost (+NT$113M in dividends).
77% of Profit: Generated by TSMC alone (NT$7.70B spent yielding NT$7.77B in total gains).
100% Win Rate: All eight holdings ended profitable, including Hon Hai (NT$1.86B) and ASE Technology (NT$861M).
Why It Matters:
Strategic: Demonstrates how effectively public stabilization operations can shield local markets from trade-war policy shocks, while illustrating TSMC’s role as the primary anchor of Taiwan’s financial stability.
Investment Read-Through: Highlights the structural concentration risk inherent in the TAIEX index, where broader market stability remains deeply tied to a single leading semiconductor manufacturer.
Global Market Watch is a daily market intelligence report produced in collaboration between TechSoda and FCC Partners, a Taiwan-based investment bank. We curate and analyze the latest developments across AI, semiconductors, drones & defense, robotics & industrial automation, and policy & geopolitics to keep you informed of the trends shaping global markets.
Disclaimer: Any discussion of stock prices, market performance, or specific companies in this article is provided solely for informational and educational purposes. It should not be construed as investment, financial, or trading advice, nor as a recommendation to buy, sell, or hold any securities. Readers should conduct their own research and consult a qualified financial adviser before making any investment decisions.