
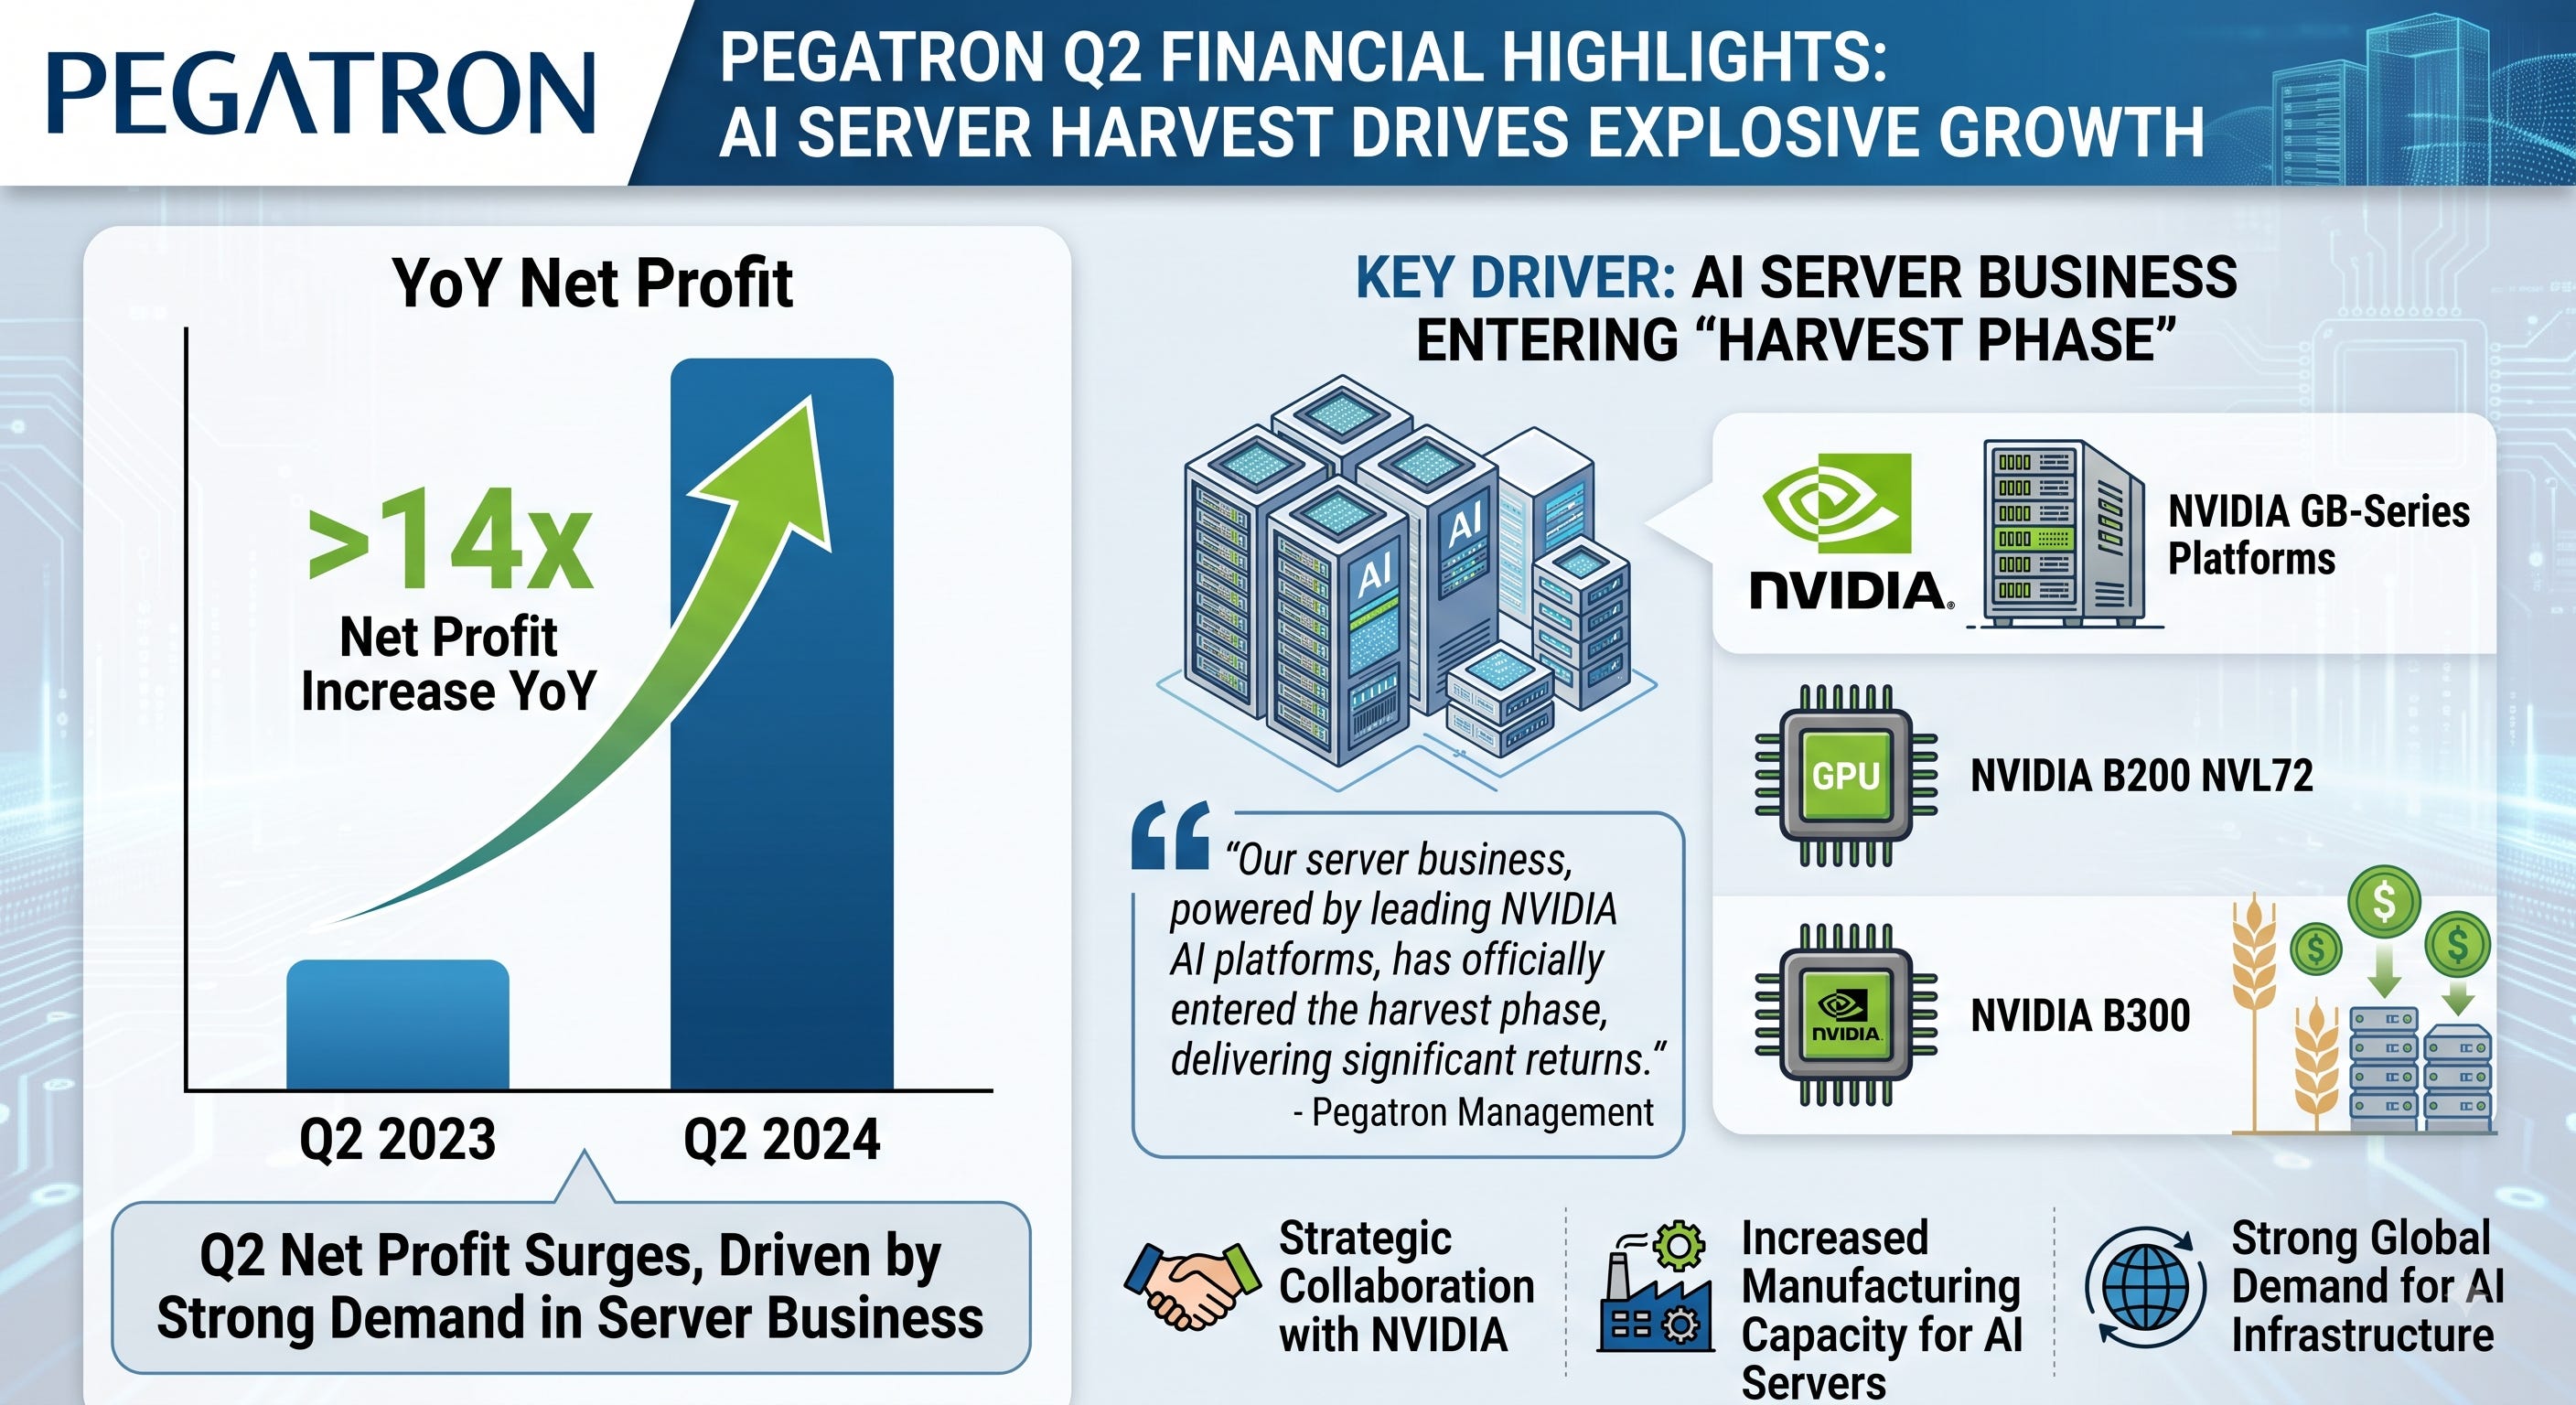
Foxconn said its next-generation Nvidia Vera Rubin AI rack platform is entering mass-production readiness in Q3; Pegatron reports Q2 net profit up more than 14x YoY as its server business accelerates; Formosa Plastics forms a 50/50 joint venture with Japan’s Daicel Corporation to produce electronic-grade photoresist thinner; and other tech news:
I. Semiconductors
1. Formosa Plastics Forms JV With Japan’s Daicel to Localize Electronic-Grade Photoresist Thinner Production
Formosa Plastics’ (1301 TW) board approved on August 13 a 50/50 joint venture with Japan’s Daicel Corporation to build a dedicated electronic-grade photoresist thinner plant at Formosa’s Renwu complex, targeting a material where Daicel holds over 60% global share in semiconductor photoresist applications.
The Numbers:
JV registered capital of NT$1.5 billion (NT$800 million paid-in initially); Formosa Plastics investing NT$2.39 billion in the new facility, targeting mechanical completion by September 2028 and production start by December 2028.
Taiwan’s electronic-grade photoresist thinner supply was roughly 100,000 tons last year against demand of 113,000 tons - a 13,000-ton shortfall the JV is designed to close.
Demand is projected to reach 267,000 tons by 2030, an implied CAGR of about 18.8%, driven by AI, HPC, HBM and 3D NAND capacity growth.
Executive Impact:
Strategic Impact: The JV brings a critical, currently import-dependent semiconductor material in-house at a moment when AI-driven wafer starts are straining Taiwan’s specialty-chemical supply chain - Daicel’s technology plus Formosa’s local manufacturing scale directly targets the existing 13,000-ton domestic shortfall.
Investment Read-through: A multi-year capacity build (first output not until late 2028) rather than a near-term catalyst, but it signals Taiwan’s semiconductor-materials localization push extending beyond wafers and substrates into upstream specialty chemicals - a trend other materials suppliers in the photoresist/etch chemical space may look to replicate.
2. China Grinding Wheel / Yuchuan Precision Materials: Advanced-Node Price Pass-Through Lifts Margins, Fuels New Fab Investment
China Grinding Wheel (1560 TW) and Yuchuan Precision Materials (7887 TW) reported August 13 that price increases across the wafer, sputtering-target and precursor supply chain - driven by AI and advanced-node demand plus geopolitical and raw-material cost pressures - are flowing through to their financials, with China Grinding Wheel posting a record quarter and Yuchuan announcing a new fab.
The Numbers:
China Grinding Wheel Q2 consolidated revenue NT$2.49 billion (+8.75% QoQ), gross margin 40.1% (+3.5ppt QoQ), Q2 EPS NT$3.49; H1 revenue NT$4.79 billion (+23% YoY), H1 EPS NT$6.44. Sub-5nm process revenue rose 84% QoQ and now represents 61.2% of sales; top customer accounts for 63% of revenue.
Yuchuan Precision Materials July revenue NT$20.868 million (+135.76% YoY); cumulative Jan-Jul revenue NT$123 million (+96.32% YoY); H1 EPS NT$0.02.
Yuchuan plans to invest up to NT$3 billion in a new Tainan Science Park plant, expanding capacity six-to-tenfold versus its existing scale, with groundbreaking targeted for Q4.
Executive Impact:
Strategic Impact: Management at both firms frame this as a structural shift, not a cyclical restocking bounce - AI chip wafer-start volume, added process steps, and supply-chain localization are jointly driving the repricing, with China Grinding Wheel’s diamond-disc mix shift toward 2nm/1.6nm nodes and Yuchuan’s high-purity precursor demand (tied to 2nm GAA architecture) both benefiting.
Investment Read-through: China Grinding Wheel’s near-term earnings already show the advanced-node mix shift; Yuchuan’s new plant - explicitly positioned as a ‘post-2028, sub-2nm’ capacity base - is a longer-duration bet on continued leading-edge expansion, though its current single-customer concentration (63% at China Grinding Wheel) is a supply-chain risk worth flagging.
3. Union Optronics: H1 Profit Jumps 465% as 1.6T Optical Components Enter Mass Production
Union Optronics (3081 TW) held an investor briefing on August 12 reporting sharp H1 profit acceleration on AI data-center demand for its precision optical laser products, with 1.6T-related components now in mass production.
The Numbers:
Q2 revenue NT$1.221 billion (+35% QoQ, +121% YoY); Q2 gross margin 57.45% (vs. 43.33% a year earlier); Q2 net profit NT$468 million (+48% QoQ, +384% YoY); Q2 EPS NT$4.62.
H1 revenue NT$2.126 billion (+111% YoY); H1 operating profit NT$946 million (+388% YoY); H1 net profit NT$786 million (+465% YoY); H1 EPS NT$7.75.
Precision optical products, mostly laser-based, account for roughly 85-90% of revenue; depreciation held below 8-10% of revenue.
Executive Impact:
Strategic Impact: Management attributed the margin expansion to product mix, yield, pricing and utilization rather than price hikes alone, and is extending its roadmap into EML and PD products while adopting nanoimprint and new lithography techniques - positioning the company to keep pace with rising optical-transceiver speed requirements in AI data centers.
Investment Read-through: With 1.6T components already in mass production and gross margin still expanding, Union Optronics looks well-placed to keep capturing share of AI data-center high-speed optical interconnect spend; the extension into EML/PD signals an attempt to broaden beyond its current laser-product concentration.
II. Artificial Intelligence
1. Foxconn: Vera Rubin AI Rack Ramp Begins as ASIC Server Mix Climbs Toward 40%+ Share
Foxconn (2317 TW) said its next-generation Nvidia Vera Rubin AI rack platform is entering mass-production readiness in Q3 with volume shipments planned for Q4, alongside Q2 earnings reported August 13 showing continued profit growth.
The Numbers:
Q2 net profit NT$59.974 billion (+20% QoQ, +35% YoY); Q2 EPS NT$4.27; H1 net profit NT$109.893 billion (+27% YoY); H1 EPS NT$7.84.
Capex guided to rise more than 30% YoY.
Management targets roughly 50% share of the global AI rack market and over 40% share in ASIC-based AI servers; ASIC servers were about 10% of AI server revenue last year and are already running above that share so far this year.
Executive Impact:
Strategic Impact: Rotating CEO Steve Jiang said contribution from Vera Rubin should build over coming quarters ‘as product validation, supply chain and capacity fall into place,’ while CFO David Huang cautioned that Foxconn’s ASIC servers run on a customer-supplied-component model, meaning reported revenue understates the actual scale of that business.
Investment Read-through: Existing GB-series racks still have demand runway extending at least into next year, so Vera Rubin is additive rather than a replacement-cycle risk in the near term; the ASIC mix shift toward 40%+ is the more structurally important signal for margin and customer-diversification watchers, given ASIC programs typically carry different economics than merchant-GPU-based racks.
2. Taiwan Mobile: Launches NT$29.1 Billion Tender Offer to Take Systex Stake to 58%
Taiwan Mobile (3045 TW) announced August 12 that its board approved a tender offer, via wholly owned subsidiary Taiwan Fixed Network, to raise its stake in IT services firm Systex (6214 TW) from 11.86% to roughly 58%, with the offer running August 18 to October 6.
The Numbers:
Tender price approximately NT$184.5 per Systex share, a roughly 29% premium to the two companies’ closing prices and about 33% versus their trailing one-quarter average.
Total deal cap exceeds NT$29.1 billion, split into a cash component of approximately NT$14.6 billion and a stock component of over 132 million new Taiwan Mobile shares; each tendered Systex share exchanges for 0.84 Taiwan Mobile shares plus NT$92.5 in cash.
Executive Impact:
Strategic Impact: CFO and spokesperson Rosita Chang framed the deal as building a deeper ICT strategic alliance combining Taiwan Mobile’s telecom capabilities with Systex’s IT services footprint, targeting cross-selling, AI and regionalization as the three synergy pillars.
Investment Read-through: The roughly 30% premium signals Taiwan Mobile is paying up for enterprise AI/IT-services distribution rather than pure telecom growth, aiming to double its share of Taiwan’s IT services market - a read-through for other domestic system integrators that could become consolidation targets as telecom operators chase enterprise AI revenue.
3. Pegatron: Server Profit Jumps Over 1,400% YoY, Reiterates 10x Full-Year Server Revenue Target
Pegatron (4938 TW) held an investor conference on August 12, reporting Q2 net profit up more than 14x YoY as its server business - driven by Nvidia GB-series, B200, and B300 platforms - moves into what management called a ‘harvest phase.’
The Numbers:
Q2 revenue NT$274.448 billion (+12.4% QoQ, +2.7% YoY); Q2 gross margin 4.4%; Q2 net profit NT$4.488 billion (+187.5% QoQ, +1,463.8% YoY); Q2 EPS NT$1.68.
H1 revenue NT$518.553 billion (-3.9% YoY); H1 gross margin 4.4%; H1 net profit NT$6.049 billion (+31.8% YoY); H1 EPS NT$2.26.
IT-products revenue up 82% QoQ; consumer-products revenue up 57% QoQ.
Executive Impact:
Strategic Impact: Co-CEO Cheng Kuang-chih said the company is ‘very confident’ of hitting its full-year target of 10x server-revenue growth, while co-CEO Denny Deng said GB300 will remain in production alongside newer products rather than being phased out immediately, and expects servers to become a top-two-or-three revenue segment within one to two years.
Investment Read-through: The scale of the Q2 profit swing (from a low base) shows how much operating leverage AI-server ramp is providing relative to Pegatron’s legacy notebook business, which management flagged is facing margin pressure from rising CPU and memory component costs - a reminder that the server tailwind is partly offsetting, not eliminating, cost headwinds elsewhere in the portfolio.
III. Robotics & Industrial Automation
1. IKKA-KY: Takes 20.85% Stake in Yijin Precision to Enter Japan’s Humanoid Robot Supply Chain
IKKA-KY (2250 TW) said its board approved on August 12 a NT$135 million investment for a 20.85% stake in Yijin Precision, pairing its plastic-gear and injection-molding expertise with Yijin’s metal-gear and robotic-arm assembly capabilities to target Japan’s humanoid robot ‘national team’ program.
The Numbers:
Deal size NT$135 million for a 20.85% stake at NT$34.17 per share.
IKKA-KY H1 revenue NT$1.57 billion (-8.39% YoY); H1 net profit NT$30.63 million (-59.14% YoY); H1 EPS NT$0.84; cash dividend of NT$3 declared, implying a yield of about 4.98% at the current share price of NT$60.3.
Executive Impact:
Strategic Impact: The tie-up gives IKKA-KY a path from single-part automotive plastic-gear supply into full ‘metal gear + plastic gear + robot assembly’ positioning, aimed at shortening validation and mass-production lead times for humanoid-robot joint and reducer components and diversifying away from cyclical automotive-parts demand.
Investment Read-through: A relatively small-ticket stake (NT$135 million) rather than a scale commitment, but it signals Taiwan’s precision auto-parts suppliers actively repositioning toward humanoid-robot component supply chains as a new demand pool - worth tracking whether the partnership converts into confirmed orders from Japanese humanoid-robot integrators.
2. Hiwin: Begins Shipping Humanoid Robot Arm Modules as Taiwan Supply Chain Enters Volume Production
Hiwin (2049 TW) Chairman Cho Wen-heng said the company has begun shipping humanoid robot arm modules to both domestic and international robot contract manufacturers and is now taking larger orders, as Taiwan’s robotics component supply chain shifts from prototype validation to volume production ahead of the Taiwan Robot & Smart Automation show on August 19.
The Numbers:
Chinese humanoid-robot maker Unitree Robotics is targeting full-year shipments of 10,000-20,000 units, roughly double last year’s capacity.
Agility Robotics’ Digit humanoid robot has reached an annual production capacity of 10,000 units.
Executive Impact:
Strategic Impact: Cho’s comment that Hiwin has moved ‘from customer validation to volume production’ is a leading indicator for the broader Taiwan component supply chain - ball screws, linear guides, reducers, motors, and AI-vision modules - since Hiwin’s arm modules sit directly inside the humanoid-robot joint assembly that most integrators source externally.
Investment Read-through: With both Unitree and Agility Robotics scaling toward five-figure annual unit volumes, Taiwan’s precision-motion component suppliers are positioned as the picks-and-shovels beneficiaries of humanoid-robot volume ramp regardless of which end-brand wins share - a broader and earlier-cycle read-through than betting on any single robot OEM.
IV. Drones & Defense
1. US Weighs Retroactive Ban on Certified Chinese Drones, Opening Door for Taiwan Suppliers
The US FCC is preparing to expand its restrictions on Chinese-made drones from blocking new model certifications to retroactively pulling previously certified models from the US market, targeting five categories - LiDAR, thermal imaging, agricultural spraying, swarm-flight and auto-docking-hangar-capable models - that would force existing DJI-made drones out of the US market.
The Numbers:
The source article does not disclose specific revenue, contract or market-size figures for this policy expansion - flagging rather than asserting figures not in the report.
The first wave of FCC restrictions took effect in December 2025; the current move is an expansion of that policy to a broader scope of previously certified models.
Executive Impact:
Strategic Impact: Extending the ban to already-certified models - not just blocking new entrants - would remove installed-base Chinese drones from the US government, commercial, agricultural and consumer markets simultaneously, materially accelerating the de-China-fication of the US drone supply chain beyond government procurement alone.
Investment Read-through: Taiwan’s drone and drone-component supply chain - cited beneficiaries include Thunder Tiger, AIDC, Asia Optical (optics), 格斯科技 (batteries) and 晟田科技 (precision casting) - stands to capture replacement demand across a wider addressable market than the existing government-only restrictions covered, though the timeline and scope of the retroactive rule are not yet finalized.
2. Han Kuang 42 Exercise: Military Police Integrate Drones Into First Guangfu Bridge Defense Drill
On the night of August 12-13, as part of the ninth day of the Han Kuang No. 42 live-fire exercise, Taiwan’s Military Police Command conducted its first bridge-denial drill at Guangfu Bridge (connecting Banqiao, New Taipei and Wanhua, Taipei), incorporating reconnaissance drones into a live urban-defense scenario for the first time.
The Numbers:
The drill deployed wire entanglements, anti-vehicle barriers and steel hedgehogs alongside Clouded Leopard armored vehicles mounting 40mm grenade launchers and 30mm cannons; the article does not disclose a specific drone unit count or budget figure tied to the drone-integration element.
Executive Impact:
Strategic Impact: The Military Police Command said the goal was to validate bridge-denial planning and command responsiveness; folding a reconnaissance drone into a core infrastructure-defense scenario for the first time signals the drone is moving from a niche ISR tool toward a standard element of Taiwan’s territorial-defense doctrine.
Investment Read-through: This is a doctrine/procurement-signal item rather than a company-specific catalyst - it reinforces the demand backdrop for Taiwan’s domestic drone suppliers (the same names benefiting from the US de-China-fication trend above) as the military visibly normalizes drone use across exercise scenarios, supporting the case for continued defense-drone budget allocation even as the ‘國防自主無人載具採購特別條例’ remains stuck in inter-party negotiation.
V. AI Policy & Geopolitics
1. Norway’s Sovereign Wealth Fund Boosts Taiwan Tech Exposure, TSMC Holding Value Up 47.8%
Norges Bank Investment Management (NBIM), which manages Norway’s US$2.2 trillion sovereign wealth fund, disclosed on August 11 its Taiwan equity holdings as of June 30, showing a portfolio increasingly concentrated in AI and semiconductor names even as the number of Taiwan positions declined slightly.
The Numbers:
Total value of NBIM’s Taiwan holdings rose 50.7% to NOK 612.674 billion (US$61.914 billion), versus an 8.3% rise in NBIM’s overall global equity portfolio (to NOK 16.4 trillion, roughly US$1.66 trillion).
NBIM held 333 Taiwan stocks (down 6 from year-end), adding 14 positions and dropping 20; TSMC remained the top holding at US$33.525 billion (+47.8%), followed by MediaTek at US$3.183 billion (roughly 3x), Delta Electronics at US$1.756 billion (+75%), Foxconn at US$1.219 billion (+1.5%) and Yageo at US$1.120 billion (+426%).
Executive Impact:
Strategic Impact: The reshuffle shows MediaTek jumping to NBIM’s second-largest Taiwan holding and Yageo surging from 18th to 5th, while ASE Technology displaced CTBC Financial as the sixth-largest position - a pattern consistent with global capital rotating further into AI/semiconductor supply-chain names and away from Taiwan’s traditional and auto-related sectors.
Investment Read-through: A large, methodical sovereign investor materially increasing conviction-weighted exposure to Taiwan’s AI/chip complex - TSMC’s position value still rose sharply even as its portfolio weight edged down from 1.77% to 1.70%, reflecting price appreciation more than active buying - supports the broader thesis that international institutional capital is treating Taiwan as a core AI-supply-chain allocation, not just a trading vehicle.
2. Taiwan Listed Companies’ H1 Profit Surges 138% Past NT$1 Trillion, Analysts See Full-Year Above NT$7 Trillion
With 1,109 listed companies having reported results, Taiwan brokerages First Securities Investment Consulting and Taishin Securities Investment Consulting said on August 13 that aggregate H1 profit has surged past NT$1 trillion as the TAIEX closed at a rebound high of 45,518 on August 12, up 397 points and breaking above its July 17 post-selloff high.
The Numbers:
Q2 aggregate profit NT$732.608 billion (+257.87% YoY); H1 aggregate profit NT$1.24 trillion (+138.38% YoY); full-year profit projected above NT$7 trillion (+56% YoY), with Q3 and Q4 profit forecast at NT$1.89 trillion and NT$1.9 trillion respectively.
Q2 aggregate revenue NT$14.2 trillion, with Q3/Q4 projected at NT$15.4 trillion and NT$16.5 trillion; Taiwan 50 Index constituent profit growth estimated at 50-60% YoY.
Executive Impact:
Strategic Impact: First Securities Investment Consulting chairman Huang Yi-ting and Taishin Securities Investment Consulting general manager Huang Wen-ching both attributed the acceleration to the AI supply chain, with Huang Wen-ching specifically flagging foundry, passive-component and memory price increases as the sectors carrying H2 momentum, and projecting the TAIEX could challenge its historical high of 48,218 in August.
Investment Read-through: The Q2 YoY comparison (+257.87%) is flattering against a relatively soft year-ago base, so the sequential Q3/Q4 forecast trajectory (NT$1.89tn, NT$1.9tn - roughly flat quarter-over-quarter) is arguably a more reliable read on underlying momentum than the YoY headline; foundry, passive components and memory are the specific sub-sectors analysts are flagging as still-underappreciated beneficiaries of the pricing cycle.
3. Foreign Investors Pivot to Taiwan Over South Korea as Earnings Resilience Wins Out
Foreign investors turned net buyers of Taiwan equities in August (US$1.7 billion) while remaining net sellers of Korean equities (US$6.2 billion), ending a six-week Taiwan-selling streak, as strategists at Société Générale and GMO said Taiwan’s earnings quality and lower cyclicality are winning out over South Korea following July’s regional selloff.
The Numbers:
Taiwan’s TAIEX rallied 55.8% and South Korea’s KOSPI rallied 50.6% from their July lows through August 11; analysts have raised full-year Taiwan corporate profit estimates by 9.5% versus 7.4% for Korea; TSMC alone is seen with roughly 20% further share-price upside; Taiwan’s index has gained nearly 700 points and Japan’s Nikkei more than 1,200 points in the recent rally, versus Korea’s roughly 5% gain.
Executive Impact:
Strategic Impact: GMO portfolio manager Warren Chiang said ‘Taiwan corporates are of very high quality... every component in an iPhone comes from Taiwan,’ while Société Générale equity strategist Frank Benzimra said Taiwan’s tech sector, anchored by foundries like TSMC, is less cyclically exposed than Korea’s memory-chip-heavy market, which is also facing pressure from leveraged single-stock ETF trading.
Investment Read-through: The comparison functions as an implicit endorsement of Taiwan’s foundry-centric model over Korea’s memory-cycle-exposed model at a moment when global capital is actively choosing between the two as the primary non-US AI-hardware allocation - a positioning signal for TSMC and its closest supply-chain peers rather than a one-off flow statistic.
Global Market Watch is a daily market intelligence report produced in collaboration between TechSoda and FCC Partners Asia, a Taiwan-based investment bank. We curate and analyze the latest developments across AI, semiconductors, drones & defense, robotics & industrial automation, and policy & geopolitics to keep you informed of the trends shaping global markets.
Disclaimer: Any discussion of stock prices, market performance, or specific companies in this article is provided solely for informational and educational purposes. It should not be construed as investment, financial, or trading advice, nor as a recommendation to buy, sell, or hold any securities. Readers should conduct their own research and consult a qualified financial adviser before making any investment decisions.